In this guide 11 sections
- 1 What Are the Deposit Rules a Landlord Must Follow?
- 2 How Much Deposit Can You Take?
- 3 What Is the Prescribed Information and When Must You Serve It?
- 4 Which Deposit Scheme Should You Use?
- 5 What Happens If You Get Deposit Protection Wrong?
- 6 Can a Late Deposit Still Be Put Right?
- 7 What Happens to the Deposit When the Tenancy Ends?
- 8 How Does a Deposit Dispute Get Decided?
- 9 What Do Deposit Failures Look Like in Practice?
- 10 What Does a Deposit Not Cover?
- 11 What Should You Do in the First 30 Days?
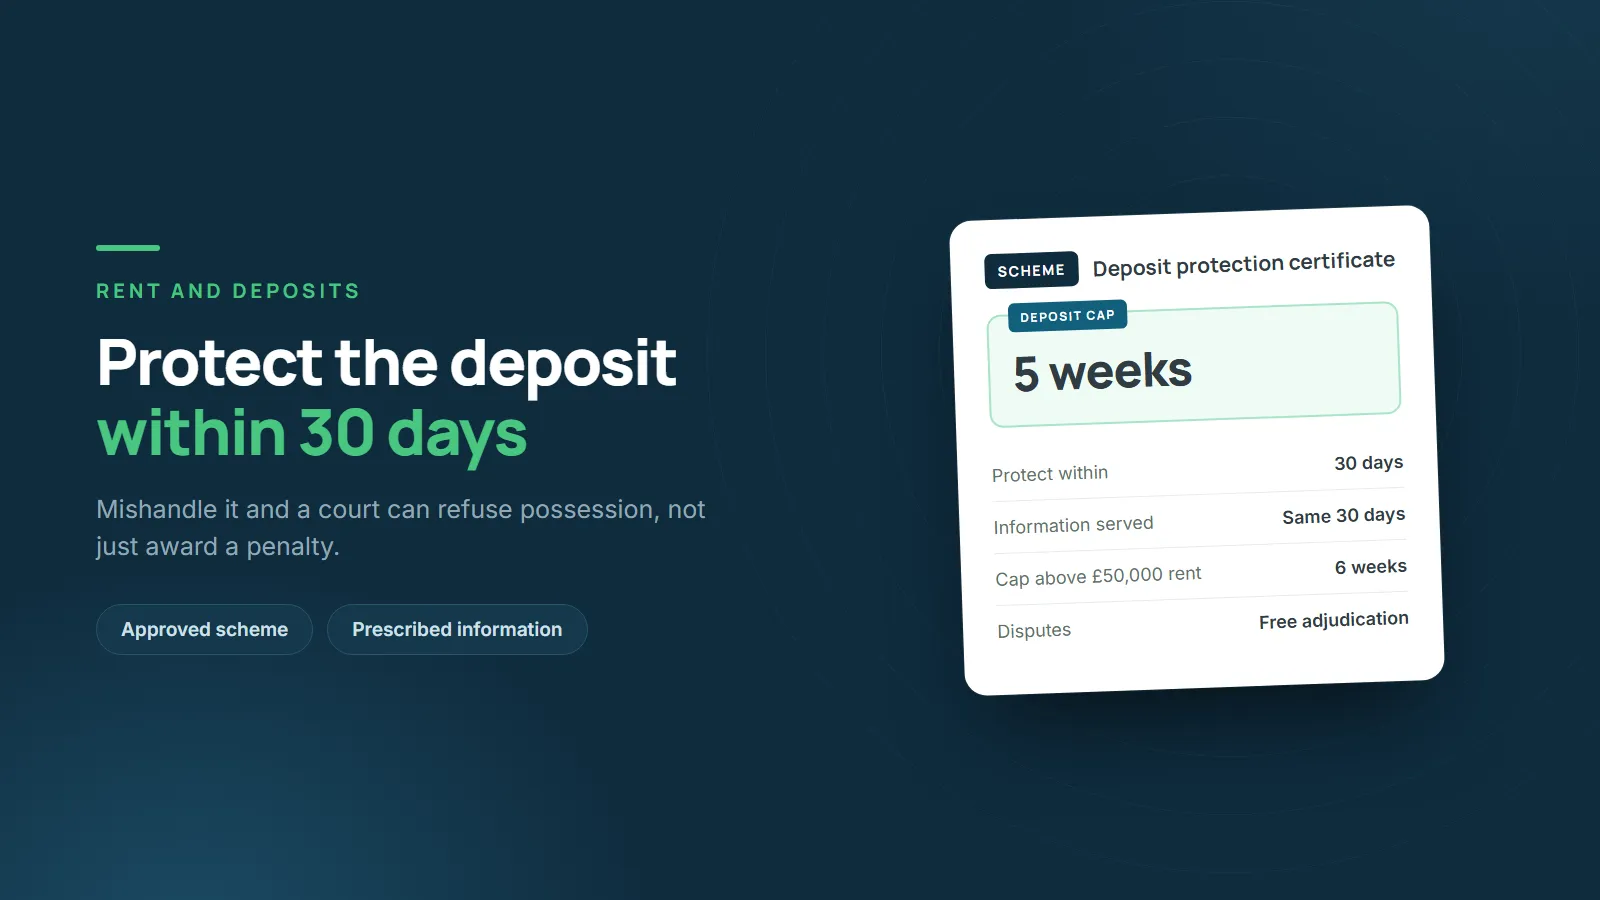
A deposit must be placed in a government-approved scheme within 30 days of receiving it, and the prescribed information given to the tenant inside the same 30 days.
That much has been settled law since 2007, and most landlords know it. What changed on 1 May 2026 is the price of getting it wrong.
A deposit failure now bars a possession order on almost every ground, not just a section 21 notice. It is the quietest of the Renters’ Rights Act changes and one of the most expensive.
It is also widely described wrongly. The common line is that a late deposit blocks possession forever.
The statute does not say that, and the distinction is the difference between a fixable problem and a permanent one.
What Are the Deposit Rules a Landlord Must Follow?
Four duties: take no more than the cap, protect the money within 30 days, serve the prescribed information within 30 days, and return it within 10 days of agreeing the figure.
The four deadlines
Every one of them runs from a different event, which is why a single diary entry is not enough.
| Duty | Deadline, and what starts it | Source |
|---|---|---|
| Stay inside the deposit cap | At the point you take it, tested again on renewal | Tenant Fees Act 2019, Sch 1 para 2 |
| Protect the deposit in a scheme | 30 days from receiving the money | Housing Act 2004, s 213(3) |
| Serve the prescribed information | 30 days from receiving the money | Housing Act 2004, s 213(6) |
| Return the deposit | 10 days from agreeing the amount | GOV.UK |
Both 30 day clocks start when the money arrives, not when the tenancy starts. Taking a deposit three weeks before move-in leaves nine days, not thirty.
The duty follows you, not your agent
If your agent protects the deposit, the obligation is still yours. Ask for the scheme certificate and the prescribed information they served, and keep both.
An agent’s failure is a defence against nobody. The claim under section 214 is brought against the landlord.
A deposit does not have to be called a deposit
Section 213(8) defines it by function: money held as security for the tenant’s obligations or liabilities. A payment labelled a bond, a retainer or a damage fund is a deposit if it works like one.
How Much Deposit Can You Take?
Five weeks’ rent where the annual rent is under £50,000, six weeks where it is £50,000 or more, with the excess a prohibited payment.
The cap, and how it is actually calculated
Schedule 1 of the Tenant Fees Act 2019 does not work in months. It defines one week’s rent as the annual rent divided by 52, then multiplies by five or six.
On a £1,200 a month tenancy, the annual rent is £14,400. One week is £276.92, so the cap is £1,384.61.
Rounding up to £1,400 because it looks like a tidier number puts you over.
The band is tested again at renewal
The £50,000 test applies to the annual rent “immediately after its grant, renewal or continuance”. A tenancy that crosses £50,000 on renewal moves into the six week band from that point.
This cuts both ways, and it is the part most often missed on higher value lets.
Holding deposits are capped separately
A holding deposit is capped at one week’s rent, calculated the same way, and it has its own rules in Schedule 2 about when it must be repaid. It is not part of the tenancy deposit until you apply it as one.
Rent in advance is now restricted too
The Act inserted a new paragraph into Schedule 1: rent payable before an assured tenancy is entered into is a prohibited payment. Asking for six months up front is no longer a workaround for a thin deposit.
Related: Rent guarantee insurance
A non-money deposit can never be required
Section 213(7) prohibits requiring a deposit of property rather than money. GOV.UK confirms a valuable item such as a car or a watch does not go into a scheme, because it should not have been taken as a deposit at all.
This one has no cure through protection. Under section 215(6) possession is barred until the item is returned.
What Is the Prescribed Information and When Must You Serve It?
A prescribed set of details about the scheme and the deposit, in the prescribed form, within the same 30 days.
The ten items
GOV.UK lists what must be given. Missing one line is as much a breach as missing the whole document.
| # | Item |
|---|---|
| 1 | The address of the rented property |
| 2 | How much deposit the tenant has paid |
| 3 | How the deposit is protected |
| 4 | The name and contact details of the scheme, and of its dispute resolution service |
| 5 | Your name and contact details, or your letting agency’s |
| 6 | The name and contact details of any third party who paid the deposit |
| 7 | Why you would keep some or all of the deposit |
| 8 | How to apply to get the deposit back at the end of the tenancy |
| 9 | What to do if the tenant cannot get hold of you at the end of the tenancy |
| 10 | What to do if there is a dispute over the amount to be returned |
Item 4 is one requirement covering two sets of contact details, and both have to be there. Item 7 needs a reason, not a formula: GOV.UK’s own example is damage the tenant caused that you need to fix.
It goes to the payer as well as the tenant
Section 213(5) requires the information to go to “the tenant and any relevant person”, which section 213(10) defines as anyone who paid the deposit on the tenant’s behalf.
A parent or an employer who paid the deposit is a relevant person. Serving only the tenant is a breach, and on student and relocation lets it is the single most common one.
Related: Student landlord insurance
Landlords lose on this more often than on protection
Protecting the money is a transaction with a receipt. Serving the information is a piece of paperwork with no automatic audit trail, which is why it is the one that goes missing.
Serve it in writing, keep a dated copy, and record how it was sent.
Which Deposit Scheme Should You Use?
Any of the three approved schemes. The real choice is custodial or insured, and that is a cash flow decision rather than a compliance one.
The two models
The tenant’s protection is identical under both. What differs is who holds the money and who pays.
| Custodial | Insured | |
|---|---|---|
| Who holds the money | The scheme | You or your agent |
| Cost to the landlord | Free | A fee per deposit |
| Cash available to you during the tenancy | No | Yes |
| At the end of the tenancy | The scheme releases it | You must repay it, and pass disputed sums to the scheme |
| Dispute resolution | Free | Free |
| Suits | Most landlords | Those with a reason to hold the cash |
The three approved schemes
GOV.UK lists the approved schemes for England and Wales: the Deposit Protection Service, mydeposits, and the Tenancy Deposit Scheme. Scotland and Northern Ireland have separate schemes.
All three offer both models. All three provide custodial protection free and dispute resolution free.
None of them publishes a full price list
This is worth saying plainly, because it is the question landlords ask and no source answers. On the schemes’ own sites, custodial protection is free and insured protection is described as a fee, but the insured price is not published.
The Deposit Protection Service states free custodial protection and “Insured protection for a small fee”, with no annual membership or renewal charge. mydeposits states free custodial protection and a fee for insured, with a discount for National Residential Landlord Association members.
So the only reliable way to compare insured cost is to get a current figure from each scheme directly. Any specific price quoted in a guide, including any figure you find elsewhere on a blog, is a snapshot that may already be stale.
What actually decides it
If you have no need to hold the money, custodial is free, removes the end of tenancy repayment duty from you, and takes the cash handling risk away. That is the default for most single property landlords.
Insured makes sense where the deposit is genuinely needed in the business, and you accept a fee plus a repayment obligation in exchange.
What Happens If You Get Deposit Protection Wrong?
Two separate consequences, with two different triggers and two different cures. Conflating them is the most common mistake in this area.
The penalty, and the possession bar, are different tests
This is the table that matters. It is drawn straight from the two sections.
| Penalty, section 214 | Possession bar, section 215 | |
|---|---|---|
| What triggers it | Missing the 30 days under s 213(3) or (6) | The deposit not being held in a scheme, scheme requirements unmet, or prescribed information not given |
| Who raises it | The tenant, or whoever paid the deposit | It arises as a bar on your own possession claim |
| Where | The county court | The possession hearing |
| Outcome | The court must order 1 to 3 times the deposit, payable in 14 days | No possession order |
| Can late compliance fix it | No | Largely yes, see below |
| Exceptions | None | Grounds 7A and 14, or deposit returned, or a s 214 claim concluded |
The penalty is mandatory, the amount is not
Section 214(4) says the court “must” order the landlord to pay “not less than the amount of the deposit and not more than three times the amount of the deposit”, within 14 days of the order.
So once a breach is established the award is not discretionary. Only its size is, between one and three times.
A former tenant can still bring it
Section 214(1A) applies subsection (1) to ended tenancies, with the reference to the tenant reading as a person who was a tenant. There is no separate limitation period written into section 214.
GOV.UK says a tenant can claim “at any time during the tenancy”. That is a simplification of the statute rather than the limit, and it is why a deposit mishandled on a tenancy that ended years ago is still a live exposure.
The possession bar is much wider than section 21 was
Before 1 May 2026, a deposit failure blocked a section 21 notice. Section 21 is gone, and the replacement section 215 says the court “may make an order for possession… only if” the deposit conditions are met.
The exceptions are narrow. Section 215(4) disapplies the bar only for possession on Ground 7A or Ground 14, the serious antisocial behaviour grounds.
Every other ground, including rent arrears, is caught.
Related: Section 8 grounds for possession
Can a Late Deposit Still Be Put Right?
For possession purposes, usually yes. The statute expressly allows late compliance, which is the opposite of what most guidance implies.
What section 215(2) actually says
The possession condition is that the scheme’s initial requirements “have been complied with (whether or not within the period mentioned by section 213(3))”.
That parenthesis is doing a great deal of work. For the possession gate, Parliament asked whether the deposit is now properly protected, not whether it was protected on time.
The gate is about the current position
Section 215(1) uses the present tense: the deposit “is being held in accordance with an authorised scheme”. Section 215(3) requires the prescribed information requirements in section 213(5) and (6)(a) to have been met, which are the content and form requirements.
Notably, section 215(3) does not cite section 213(6)(b), the 30 day deadline for the information. The drafting points the same way as subsection (2).
The two routes out, spelled out
Section 215(5) removes the bar where either the deposit has been returned in full or with agreed deductions, or a section 214 application has been determined, withdrawn or settled.
So there are three practical positions: put the protection right, return the money, or let the tenant’s claim conclude.
What late compliance does not fix
It does not touch section 214. The penalty attaches to the missed deadline, and protecting on day 40 does not unmake the failure on day 31.
This is the honest summary: a late deposit is usually a fixable possession problem and a permanent penalty exposure.
Take advice before acting on this
The reading above is what the sections say, and the interaction between late prescribed information and section 215(3) is exactly the kind of point that gets tested in court. If you have a live breach and need possession, this is a solicitor’s question, not a website’s.
What Happens to the Deposit When the Tenancy Ends?
You agree the deductions and return the money within 10 days of that agreement, or the disputed part goes to the scheme.
The 10 day clock starts at agreement
GOV.UK is specific: the deposit must be returned within 10 days of you and the tenant agreeing how much they get back. The clock starts at agreement, not at the end of the tenancy.
Which means a landlord who never engages never starts the clock, and that is not a safe place to sit. The schemes have their own deadlines for responding to a tenant’s claim, and missing them can see the full amount released.
Return the undisputed part immediately
If you are claiming £300 of a £1,400 deposit, send back the £1,100 now. Holding the whole sum over a partial dispute reads badly at adjudication and invites a wider challenge.
Insured schemes require you to hand over the disputed sum
Under an insured scheme you hold the money, so when a dispute arises you must pass the disputed amount to the scheme to hold. That obligation is easy to overlook, and it is one of the reasons custodial suits landlords who would rather not have the duty.
Put deductions in writing, itemised
A short schedule: each item, the reason, the amount claimed, and the evidence reference. A single figure with the word “damages” next to it is close to unarguable at adjudication, in the tenant’s favour.
How Does a Deposit Dispute Get Decided?
On documents alone, by a scheme adjudicator, free of charge, with the burden of proof on whoever wants to keep the money.
It is a paper exercise
Adjudicators do not visit the property and do not interview the parties. They read what both sides send, and they decide on that.
Anything you cannot document did not happen, for these purposes.
The burden sits with you
The deposit is treated as the tenant’s money. You are the party asking to keep part of it, so you are the party who has to prove the claim.
That reverses the instinct many landlords bring to it. The tenant does not have to disprove your deduction.
Fair wear and tear, and betterment
A carpet thinning over a three year tenancy is wear. A cigarette burn is damage.
Even for genuine damage, adjudicators apportion for the age and remaining life of the item. A six year old carpet with a two year life left will not be replaced at your tenant’s expense, so expect a contribution rather than a full replacement cost.
The inventory is the case
A dated, photographed, tenant-signed inventory at check-in, and the same exercise at check-out, is what wins or loses these. Photographs with visible dates, meter readings, and the condition of carpets, walls and appliances.
Without both ends of that comparison, an adjudicator has nothing to measure against and the deduction usually fails.
What Do Deposit Failures Look Like in Practice?
Both of these are failures, because the failures are what the case law and the adjudications are made of.
A late protection, claimed after the tenant left
A landlord takes a £1,400 deposit on 3 March, gets busy, and protects it on 6 April. Thirty four days.
The tenancy runs two years and ends normally. Eight months later the former tenant applies under section 214, relying on subsection (1A), and the court orders two times the deposit: £2,800, payable within 14 days.
The landlord had protected the deposit and had the certificate. None of that mattered, because the breach was the timing and the timing cannot be undone.
Prescribed information served on the tenant but not the payer
A landlord lets to a student whose father pays the £1,100 deposit by bank transfer. The deposit is protected on day four, and the prescribed information is emailed to the tenant on day five.
Faultless, apparently.
Two years later the landlord needs possession for arrears under Ground 8. At the hearing the tenant’s adviser points out that the father was a relevant person under section 213(10) and never received the prescribed information.
Section 215(3) is not satisfied, Ground 8 is not one of the two exceptions, and no possession order is made. The landlord serves the information on the father, re-files, and loses a full possession cycle to a line in a definition.
Related: Landlord legal expenses insurance
What Does a Deposit Not Cover?
Five or six weeks of rent against a void, arrears and damage together. It was never designed to carry that, and it does not.
Do the arithmetic once
On a £1,200 a month tenancy the deposit caps at roughly £1,385. Three months of arrears is £3,600 before you have repaired anything or paid a solicitor.
The deposit closes maybe a third of a bad outcome, and only if the adjudicator awards you all of it, which is not the usual result.
What the deposit cannot reach at all
Loss of rent while the property is unlettable after a fire or a flood. Legal costs of a possession claim.
Liability to a third party. Malicious damage beyond the deposit sum.
Each of those is an insurance question rather than a deposit question, and the deposit’s existence does nothing about any of them.
Where cover actually sits
Rent arrears and the cost of getting possession sit with rent guarantee and legal expenses cover. Damage beyond the deposit sits with buildings and contents cover, including accidental and malicious damage where you add it.
Comparing insurance for landlords across the UK properly is the part of this that actually changes the arithmetic. Getting the deposit right protects your possession claim, but it does not protect your income.
Related: Compare buy-to-let insurance
What Should You Do in the First 30 Days?
Protect, inform every payer, document, diarise. All four inside the month, and keep the evidence together.
The checklist
Check the deposit is inside the cap for the band the annual rent puts you in, then protect it and download the certificate. A deposit that was inside the cap when you took it can fall outside it after a rent increase.
Serve the prescribed information on the tenant and on anyone who paid on their behalf, in writing, and keep a dated copy.
Then build the inventory: every room photographed, meter readings, appliance condition, tenant signature.
The same run-up is when right to rent checks have to be done, because those have to happen before the tenancy begins rather than alongside it.
Diarise both ends
The 30 day window at the start, and the scheme response deadlines at the end. Both are avoidable failures and both are ordinary calendar entries.
Keep one compliance pack
Deposit certificate, prescribed information and proof of service, gas safety record, electrical report, energy certificate, and the government information sheet. This is the bundle a possession claim stands or falls on.
Related: What happened to section 21?
If you think you already have a breach
Do not serve notice and hope. Establish what was done and when, get the protection and the information right now, and take advice on whether to return the deposit before you rely on a possession ground.
The order of those steps matters, and section 215 gives you more room than most guidance suggests.