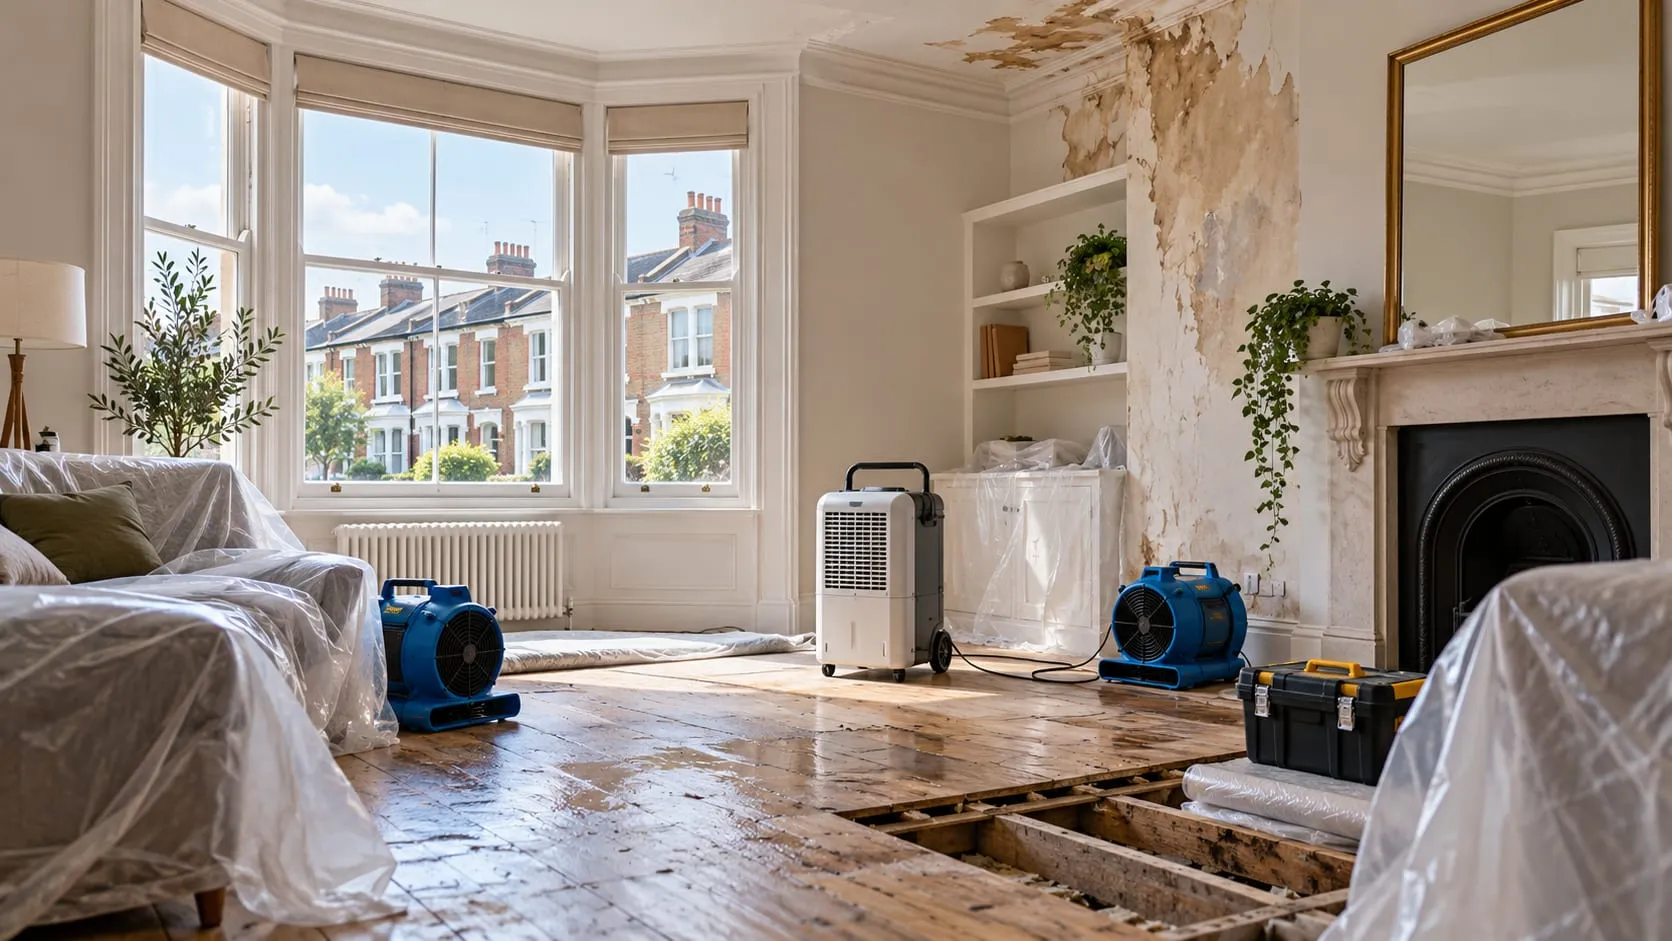
Cover when the property is uninhabitable
Loss of Rent Insurance
Cover for the rent you lose while a let property cannot be lived in after a fire, flood or other insured event.
- Rent replaced while the property is being repaired
- Alternative accommodation for tenants often included
- Compare quotes from 40+ providers
Partnered with Quotezone
What being partnered with Quotezone means LandlordQuote is a trading style of Simply Quote Comparison Ltd. We are partnered with Quotezone, a trading style of Seopa Ltd (FCA FRN: 313860). As an Introducer Appointed Representative of Seopa Ltd, we may be paid a commission if you request a quote through this website. We do not provide advice or make recommendations. Your choice of provider is entirely your own.Compare landlord insurance and deals from industry leading providers, including













01
What Is Loss of Rent Insurance?
Loss of rent insurance replaces the rental income you lose while a let property cannot be lived in following an insured event, such as a fire or a flood.
It sits on the buildings side of a landlord policy. The buildings section repairs the property, and this section covers the income lost while that happens.
Most landlord insurance options in the UK include it automatically alongside buildings cover, usually capped at a percentage of the sum insured.
02
How Do You Compare Loss of Rent Insurance Quotes?
Check whether it is included or optional, how the limit is expressed, and how long the indemnity period runs.
- 1
Find out whether you already have it
Many landlord policies include it automatically. Read the schedule before buying anything extra.
- 2
Check how the limit is calculated
Some policies express it as a percentage of the buildings sum insured, others as a number of months of rent. The two produce very different figures on the same property.
- 3
Set the indemnity period realistically
Think about how long a full rebuild would actually take, including insurer assessment, planning and finding a builder. Twelve months disappears quickly after a serious fire.
- 4
Check whether rehousing is included
If you are obliged to accommodate the tenant elsewhere, find out whether that cost sits inside the same limit as the rent.
03
What Does Loss of Rent Insurance Cover?
It covers the rent for as long as the property is uninhabitable, and often the cost of housing the tenant elsewhere while the tenancy continues.
The rent itself
The insurer pays the rent you would have received, up to the limit and for the indemnity period. Payments usually run monthly while the works are under way.
Alternative accommodation
Where the tenancy continues and you are obliged to rehouse the tenant, many policies meet those costs. In a serious fire this can exceed the rent itself.
The insured events behind it
The trigger has to be a peril covered by the buildings section, such as fire, flood, storm or escape of water. If the buildings claim fails, this section fails with it.
Why the tenancy matters
Most tenancy agreements suspend the rent when a property becomes uninhabitable. That clause is what creates the loss this cover meets.
Compare in one place
See what landlord cover is available for your property.
One set of questions, quotes back from UK providers.
04
How Does It Differ From Rent Guarantee?
Loss of rent answers when the building fails, while rent guarantee answers when the tenant fails. Holding one does not give you the other.
The two compared
Landlords regularly believe they hold one when the schedule shows the other, and the distinction only surfaces at claim time.
| Loss of rent | Rent guarantee | |
|---|---|---|
| Trigger | Property is uninhabitable | Tenant stops paying |
| Typical cause | Fire, flood, escape of water | Job loss, dispute, default |
| Where it sits | Part of buildings cover | Optional add-on |
| Conditions | An insured event under the policy | Referencing and a written tenancy |
| Legal costs | Not included | Usually included |
Which one you need
If the worry is a burst pipe making the flat unusable for months, that is loss of rent. If the worry is a tenant losing their job, that is rent guarantee. Most landlords end up holding both, because they protect against completely different failures.
05
How Much Loss of Rent Cover Do You Need?
Work out the annual rent, then decide how many months of it you would need if the property were unusable for a long period.
Start from the annual rent
A property let at £1,200 a month produces £14,400 a year. A twelve month indemnity period on that rent is a £14,400 exposure, before any rehousing costs.
Understand the percentage basis
Where cover is expressed as a percentage of the buildings sum insured, check what that produces in pounds. On a modest rebuild figure with a high rent, the percentage can fall short.
Think about how long a rebuild really takes
Assessment, agreeing a schedule, tendering and the work itself all add up. Listed buildings and flats within blocks take longer than a standard house.
Flats take longer than houses
Damage in a block often involves the freeholder’s policy, shared contractors and access to other flats. That co-ordination regularly doubles the time a house would take.
Add rehousing to the calculation
If the tenancy continues and you must house the tenant elsewhere, that runs alongside the lost rent. Where both come from one limit, the limit needs to cover both.
06
What Is Not Covered by Loss of Rent Insurance?
Void periods, tenants who stop paying, damage that is not an insured peril and losses beyond the indemnity period all sit outside the cover.
-
Ordinary void periods
A gap between tenancies is a commercial risk, not an insured event. No policy pays rent simply because the property is empty.
-
Tenants who default
A tenant who stays but stops paying is not a loss of rent claim, because the property remains habitable. That is what rent guarantee exists for.
-
Uninsured causes
If the damage is not covered by the buildings section, the rent is not covered either. Gradual damp and poor maintenance are the usual examples.
-
Losses after the indemnity period ends
Once the period expires, payments stop even if the property is still unusable. This is why setting the period realistically matters more than the headline limit.
07
How Does a Loss of Rent Claim Work?
The buildings claim is agreed first, then rent is paid monthly while the property is uninhabitable, up to the limit and the indemnity period.
A worked example
A kitchen fire makes a house let at £1,100 a month uninhabitable.
The rebuild takes seven months, and the policy has a twelve month indemnity period. The tenancy suspends the rent while the property is unusable, so you claim £1,100 a month for seven months. If the tenancy continued and you rehoused the tenant, those costs are assessed alongside.
Evidence the rent
The tenancy agreement, recent rent statements and bank records. A property let informally or below market rent is harder to evidence.
Keep the tenant in the picture
Whether the tenancy continues or ends changes what you can claim. Section 11 of the Landlord and Tenant Act 1985 keeps the repairing duty with you throughout, so the works remain your responsibility.
08
How Much Does Loss of Rent Cover Cost?
Where it is included as standard it adds nothing. Where it is optional, it is usually a small proportion of the overall landlord premium.
What moves the price
- 1 Annual rent insured Higher rent, higher exposure and premium
- 2 Indemnity period Longer periods cost more
- 3 Rebuild complexity Listed and flat conversions raise it
- 4 Flood and subsidence risk Raises the chance of a long closure
- 5 Whether rehousing is included Adds to the limit needed
- 6 Property type Blocks and HMOs can take longer to reinstate
Check before you pay twice
Buying a standalone product when your buildings policy already includes the cover is a common waste. Guidance from the Association of British Insurers is a useful reference on what landlord policies typically include.
09
How Can You Reduce the Risk of a Long Closure?
Prevent the claims that cause closures, and make sure the property can be reinstated quickly if one happens.
Deal with water risks first
Escape of water causes more residential closures than fire. Servicing the boiler, checking appliance hoses and replacing ageing pipework prevents most of them.
Keep the rebuild figure accurate
An accurate sum insured speeds up agreement with the insurer and avoids a proportionate reduction. It also affects the loss of rent limit where that is set as a percentage.
Maintain the property properly
GOV.UK sets out a landlord’s repair and safety duties, and meeting them both prevents damage and supports a claim. Unmaintained properties see more claims declined.
Report damage immediately
Early reporting gets the assessment moving and shortens the closure. Delays are the main reason an indemnity period runs out.
Questions
Frequently asked questions
What is loss of rent insurance?
It replaces the rent you lose while a property cannot be lived in following an insured event such as a fire or a flood. It is normally part of, or an option on, a landlord buildings policy.
How is it different from rent guarantee?
Loss of rent responds when the property itself is unusable. Rent guarantee responds when the property is perfectly habitable but the tenant stops paying. They cover unrelated risks.
Is it included as standard?
Many landlord policies include it automatically, often expressed as a percentage of the buildings sum insured. Others offer it as a priced option, so check your schedule rather than assuming.
How much cover do I get?
Cover is usually expressed either as a percentage of the buildings sum insured, commonly around 20 per cent, or as a set number of months of rent. Which basis applies changes the figure considerably.
How long does it pay for?
Until the property is habitable again or the indemnity period runs out, whichever comes first. Twelve months is common on residential policies, with longer periods available.
Does it cover alternative accommodation for my tenant?
Many policies include rehousing costs where the tenancy continues and you are obliged to accommodate the tenant. Check whether it sits inside the same limit as the rent itself.
What if the property was empty when the damage happened?
There has to be rent to lose. If the property was vacant with no tenancy in place, there is usually nothing to claim under this section, though the buildings damage is still covered.
Does it cover a tenant leaving early?
No. A tenant who simply leaves, or a void period between tenancies, is a commercial risk rather than an insured event.
Does the tenant still pay rent while repairs happen?
Usually not, if the property is genuinely uninhabitable. Most tenancy agreements suspend rent in those circumstances, which is exactly the gap this cover fills.
Can I claim for the mortgage rather than the rent?
The cover is based on the rent you were receiving, not on your outgoings. If the rent covers the mortgage, the effect is similar, but the calculation starts from the rent.
Does it cost anything to compare quotes here?
No. Comparing is free and there is no obligation to buy. We may be paid a fee when a policy is taken out, which does not change the price you are quoted.
Ready to compare quotes?
Cover for the rent you lose while a let property cannot be lived in after a fire, flood or other insured event.
Compare landlord insurance quotes from UK providers.