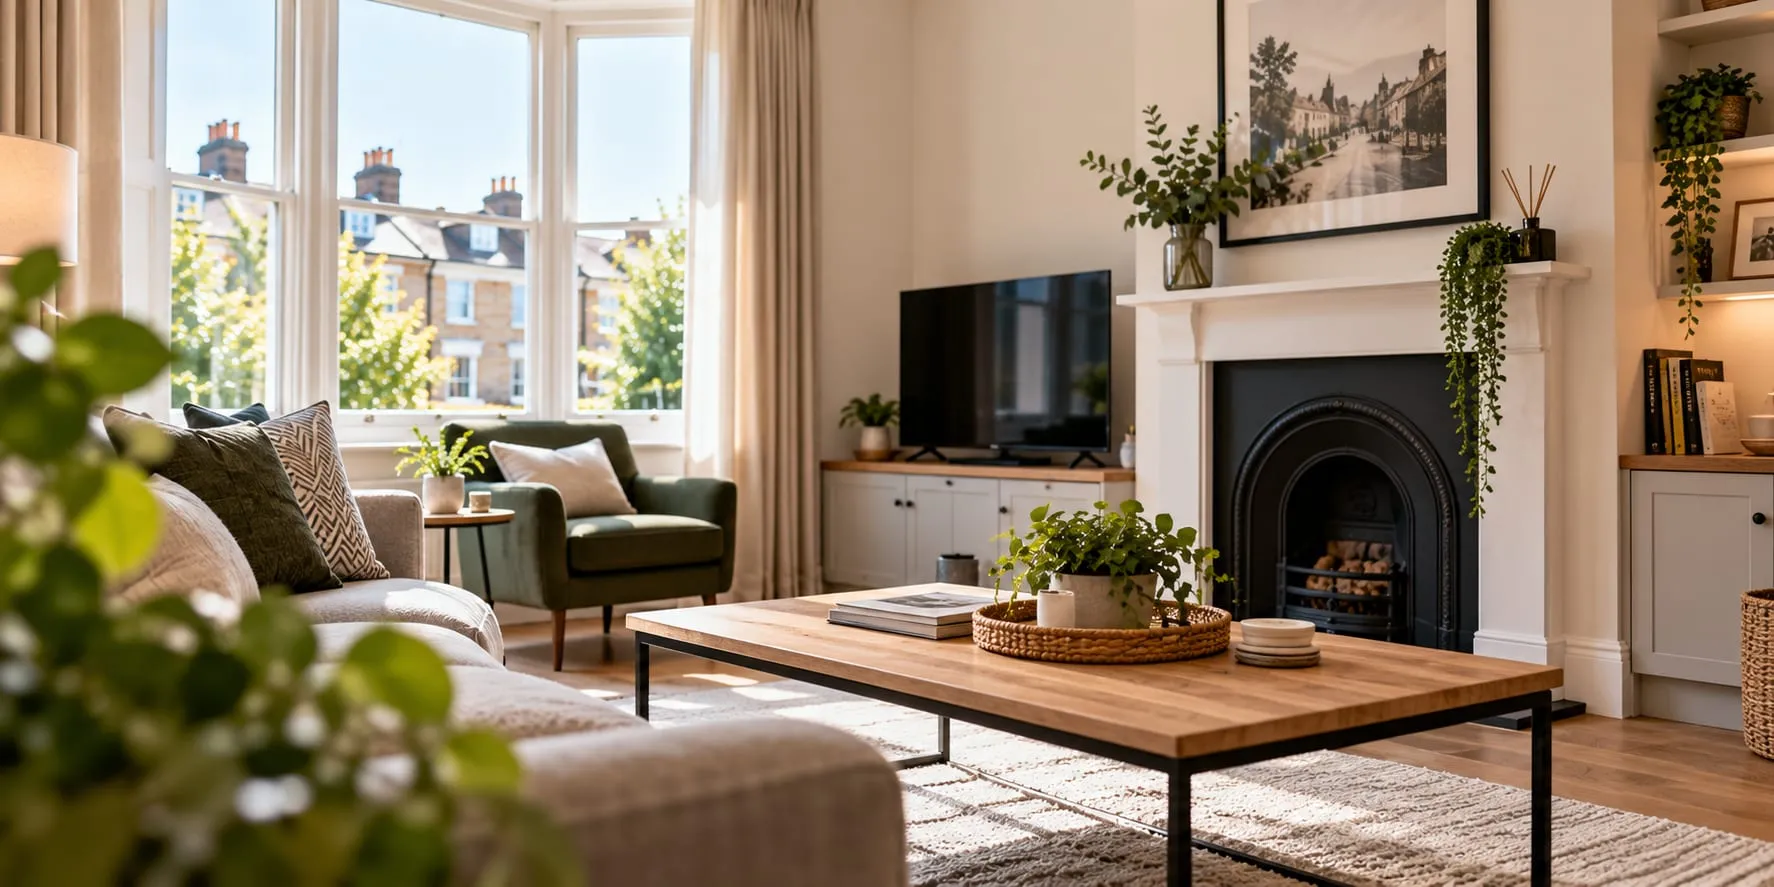
Cover for what you provide
Landlord Contents Insurance
Cover for the carpets, curtains, appliances and furniture you own inside a property you rent out, rather than your tenant’s belongings.
- Carpets, curtains, white goods and furniture you own
- Accidental and malicious damage available as options
- Compare quotes from 40+ providers
Partnered with Quotezone
What being partnered with Quotezone means LandlordQuote is a trading style of Simply Quote Comparison Ltd. We are partnered with Quotezone, a trading style of Seopa Ltd (FCA FRN: 313860). As an Introducer Appointed Representative of Seopa Ltd, we may be paid a commission if you request a quote through this website. We do not provide advice or make recommendations. Your choice of provider is entirely your own.Compare landlord insurance and deals from industry leading providers, including













01
What Is Landlord Contents Insurance?
Landlord contents insurance covers the items you provide inside a property you let, such as carpets, curtains, white goods and furniture, rather than anything belonging to your tenant.
The dividing line is ownership, not location. If you bought it and it stays when the tenant leaves, it is landlord contents.
Even on a let described as unfurnished there is usually something to insure, which is why most insurance for landlords in the UK includes a modest contents limit by default.
02
How Do You Compare Landlord Contents Insurance Quotes?
Total up what you actually provide, then compare the settlement basis, the single-item limits and whether accidental damage is included.
- 1
Inventory what you own
Walk the property and list everything you supplied, room by room. Carpets and white goods are the items landlords most often forget to count.
- 2
Price it at replacement cost
Use what it would cost to buy the same items today, not what you paid. Second-hand values are not how most policies settle.
- 3
Check the settlement basis
Find out whether the policy replaces new for old or deducts for wear and tear. Two quotes at the same price can settle very differently.
- 4
Decide on the optional extras
Accidental damage and malicious damage by tenants are usually priced separately. Decide whether the property and the tenant type justify them.
03
What Does Landlord Contents Insurance Cover?
It covers the furnishings and appliances you own against the same perils as the buildings section, with optional extensions for accidental and malicious damage.
The items themselves
Carpets, curtains, blinds, light fittings, white goods, furniture and garden furniture. In a furnished let the figure climbs quickly, and in a part-furnished one it is easy to underestimate.
The perils
Fire, flood, storm, escape of water, theft and impact, mirroring the buildings section. A single escape of water claim can take out carpets and flooring across a whole floor.
Contents in common parts
Furniture, carpets and equipment in shared hallways, stairs and laundry rooms. This matters most where several households share the building.
Optional accidental damage
Accidental damage is the extension that covers the one-off mishap: a dropped pan, a foot through a ceiling, a drill through a pipe. It is rarely included as standard.
Compare in one place
See what contents cover is available for your let.
One set of questions, quotes back from UK providers.
04
What Is the Difference Between Landlord and Tenant Contents?
Landlord contents cover belongs to whoever supplied the item. Your policy covers what you provide, and your tenant insures what they bring with them.
Who insures what
The split is usually obvious, and disputes arise mainly over items left behind by previous tenants or fitted by the tenant with permission.
| Item | Usually insured by |
|---|---|
| Carpets and curtains you supplied | Landlord |
| Cooker, fridge and washing machine you supplied | Landlord |
| Sofa and beds in a furnished let | Landlord |
| Tenant's own furniture and electronics | Tenant |
| Tenant's clothing and personal items | Tenant |
| Fitted kitchen and bathroom | Landlord, usually as buildings |
Say so in the tenancy agreement
A short clause explaining that the landlord does not insure the tenant’s belongings prevents a difficult conversation after a burst pipe. Many tenants assume they are covered.
Why it matters at claim time
If an item is not on your inventory and not obviously yours, expect questions. A dated inventory with photographs settles it.
05
How Much Contents Cover Do You Need?
Add up the replacement cost of everything you supply, room by room, at today’s prices rather than what you originally paid.
Work through it room by room
Kitchens usually carry the most value, because a cooker, fridge, freezer, washing machine and dishwasher together come to more than most landlords expect. Bedrooms and living rooms follow in a furnished let. Write the list down once and keep it with the tenancy paperwork. Updating it is far quicker than building it again.
Count the soft furnishings
Carpets, underlay, curtains and blinds across a whole property are a large number on their own. They are also the items most often destroyed by an escape of water, which is the most frequent contents claim.
Check the single-item limit
Most policies cap what they will pay for any one item, regardless of your total sum insured. A high-value appliance or a large television may need to be listed separately.
Review it when the property changes
A refurbishment, a change from unfurnished to furnished, or replacing appliances all move the figure. Reviewing it at renewal takes a few minutes and prevents a proportionate reduction later.
06
What Is Not Covered by Landlord Contents Insurance?
Wear and tear, your tenant’s possessions, undeclared high-value items and damage during long void periods fall outside a standard policy.
-
Wear and tear
A sofa that has sagged over five tenancies is a replacement cost, not a claim. Insurers separate deterioration from sudden damage, and carpets are the most common flashpoint.
-
Deliberate damage by tenants
Malicious damage is frequently excluded unless added. Where it is available, expect a separate excess and a requirement to report it promptly.
-
High-value or unusual items
Anything unusually valuable may need specifying individually. Standard policies apply a single-item limit that catches out landlords who supply expensive appliances.
-
Long periods standing empty
Cover narrows once the property has been unoccupied beyond the period in your wording, and theft cover is usually the first thing to go.
07
How Does a Contents Claim Work?
You report the loss, evidence what was there and what it was worth, and the insurer settles on the basis set out in the policy, less the excess.
- Step 1 You report the loss
- Step 2 You evidence what was there
- Step 3 The insurer settles on the policy basis
A worked example
A washing machine hose fails and soaks the carpets and underlay across a ground floor.
Replacement is quoted at £2,100 and the excess is £250. On a new-for-old policy you receive £1,850. On an indemnity basis the insurer deducts for the age of the carpets, so a five-year-old carpet might settle considerably lower.
Evidence is the whole game
A dated inventory with photographs, and receipts where you have them, is what turns a disputed claim into a paid one. Update it at every changeover.
Small losses may not be worth claiming
With an excess of a few hundred pounds, a single broken appliance is often better absorbed or taken from the deposit. Claims history affects renewal pricing.
08
How Much Does Landlord Contents Insurance Cost?
It is usually a modest addition to a landlord policy, priced on the sum insured, the tenant type and whether you add accidental damage.
What moves the price
- 1 Sum insured The main driver
- 2 Furnished or unfurnished Furnished lets cost more
- 3 Tenant type Student and shared lets are rated higher
- 4 Accidental damage Adding it raises the premium
- 5 Malicious damage by tenants Priced separately where offered
- 6 Settlement basis New for old costs more than indemnity
- 7 Property security Good locks and alarms reduce it
Why it is usually worth adding
Contents cover is generally a small proportion of a landlord policy, and a single water escape can exceed several years of the extra premium. Guidance from the Association of British Insurers is a useful reference on what contents cover typically includes.
09
How Can You Reduce Contents Claims?
Keep a proper inventory, meet the furniture safety rules, choose durable furnishings and deal with small problems before they become claims.
Keep a dated inventory
Photograph every room at the start and end of each tenancy, and record the condition of carpets and appliances. It supports both a deposit deduction and an insurance claim.
Meet the furniture fire safety rules
Upholstered furniture you supply must comply with the Furniture and Furnishings (Fire) (Safety) Regulations 1988 and carry the correct labels. Second-hand items bought for a let are the usual trap.
Choose furnishings for the tenancy, not for yourself
Hard flooring and washable finishes survive turnover better than pale carpet. Lower replacement costs mean lower sums insured and fewer claims.
Keep on top of maintenance
Appliance hoses, sealant around baths and washing machine connections cause a large share of contents claims. GOV.UK sets out a landlord’s wider safety responsibilities, and routine checks pick up most of these.
Questions
Frequently asked questions
What counts as landlord contents?
Anything you own that is not fixed to the building: carpets, curtains, blinds, white goods, furniture, light fittings and garden furniture. If it would stay with the property when a tenant moved out, it is usually yours.
Do I need contents cover for an unfurnished let?
Often yes, at a modest level. Even an unfurnished property normally comes with carpets, curtains, a cooker and a fridge, and replacing those after a fire adds up quickly.
Does it cover my tenant’s belongings?
No. Your tenant insures their own possessions under their own contents policy. Saying so in the tenancy agreement prevents an argument after a leak or a break-in.
How much cover do I need?
Add up what it would cost to replace everything you provide, at today’s prices. Most landlords underestimate it, because carpets and white goods across a whole property come to more than expected.
Is accidental damage included?
Usually not as standard. It is a common optional extension, and it is the one that covers a foot through a ceiling or a dropped pan through a hob.
What about damage caused deliberately by a tenant?
Malicious damage by tenants is often excluded from standard cover or offered as a priced option with its own excess. Read that section before assuming you are protected.
Should I claim or use the deposit?
For small amounts the deposit is usually the better route, because a claim carries an excess and may affect your renewal price. Deposits are capped, so larger losses are where insurance earns its place.
Does the policy cover items in shared hallways?
Furniture, carpets and appliances in common parts are usually covered, which matters most in HMOs and blocks. Check whether communal areas are included or need to be added.
Are furnishings I supply subject to fire safety rules?
Yes. Upholstered furniture supplied in a let must meet the Furniture and Furnishings (Fire) (Safety) Regulations 1988 and carry the relevant labels. Insurers may ask about compliance after a fire.
Is cover on a new-for-old basis?
It varies. Some policies replace new for old, others deduct for wear and tear, and many apply new for old to some items and indemnity to others such as carpets. Check which applies before comparing prices.
Does it cost anything to compare quotes here?
No. Comparing is free and there is no obligation to buy. We may be paid a fee when a policy is taken out, which does not change the price you are quoted.
Ready to compare quotes?
Cover for the carpets, curtains, appliances and furniture you own inside a property you rent out, rather than your tenant’s belongings.
Compare landlord insurance quotes from UK providers.