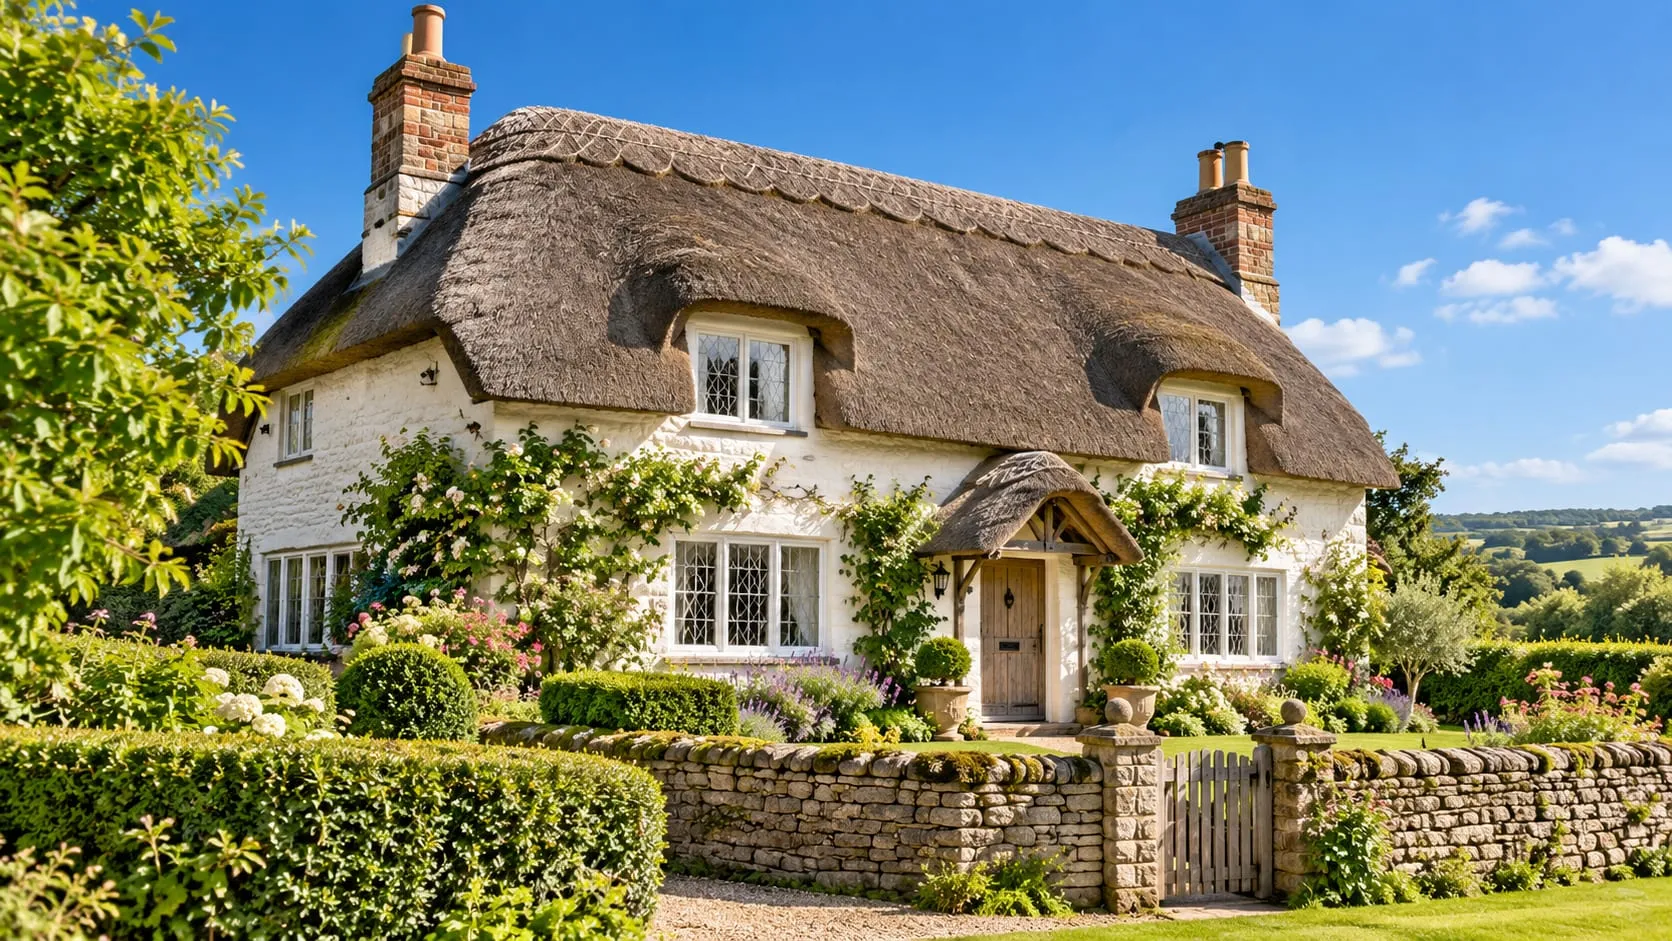
Cover when the usual insurers say no
Non-Standard Landlord Insurance
Cover for property that falls outside standard underwriting, whether because of its construction, its history, its location or yours.
- Unusual construction, flood risk and previous claims
- Declined or refused cover considered
- Compare quotes from 40+ providers
Partnered with Quotezone
What being partnered with Quotezone means LandlordQuote is a trading style of Simply Quote Comparison Ltd. We are partnered with Quotezone, a trading style of Seopa Ltd (FCA FRN: 313860). As an Introducer Appointed Representative of Seopa Ltd, we may be paid a commission if you request a quote through this website. We do not provide advice or make recommendations. Your choice of provider is entirely your own.Compare landlord insurance and deals from industry leading providers, including













01
What Is Non-Standard Landlord Insurance?
Non-standard landlord insurance covers rental property that falls outside ordinary underwriting, because of its construction, its claims history, its location or the way it is let.
The cover itself is the same: buildings, contents and liability. What differs is that the insurer has chosen to look at risks most others decline automatically.
A decline from one insurer says very little, because landlord insurance from UK providers is underwritten to different appetites rather than to a single standard.
02
How Do You Compare Non-Standard Landlord Insurance Quotes?
Gather the evidence first, because with a non-standard risk the quality of the information changes the price more than shopping around does.
- 1
Establish exactly what makes it non-standard
Construction, a past claim, the location, or the letting type. Knowing which factor is driving it tells you what evidence to gather.
- 2
Collect the supporting documents
Surveys, engineering reports, proof of remedial work and the full claims history with dates and amounts. This is what turns a decline into an offer.
- 3
Declare everything, including declines
Previous refusals, cancellations and imposed terms all have to be disclosed. Non-disclosure is far more damaging than the fact itself.
- 4
Compare the terms as well as the price
Look at the excesses, any exclusions applied to specific perils, and any conditions attached. A cheap quote with a wide exclusion may cover nothing that matters.
03
What Makes a Property Non-Standard?
Construction, condition, history, location and use are the five reasons a property leaves standard underwriting.
Unusual construction
Timber frame, steel frame, concrete panel, cob, thatch and single-skin brick all sit outside standard definitions. Some, such as certain prefabricated post-war systems, are designated defective and need a specialist insurer.
Flat roofs and unusual features
A property that is mostly flat-roofed, or has a large glazed structure, is rated differently. Insurers ask about the covering material, its age and when it was last replaced.
Listed and period property
Listing adds a reinstatement obligation that standard policies are not written for. Age alone, without listing, can also push a property outside standard terms.
Location and history
Flood risk, coastal erosion, mining areas and previous subsidence all narrow the market. So does a run of claims, even small ones.
How it is let
Holiday lets, HMOs, benefit tenants and properties standing empty each change the risk. A property can be non-standard for its letting alone while being an ordinary house.
Compare in one place
See what cover is available for an unusual property.
One set of questions, quotes back from UK providers.
04
Can You Insure a Property in a Flood Risk Area?
Almost always, though usually with a higher premium and a substantial flood excess rather than a straight refusal.
Check the risk before you quote
You can check the long term flood risk for an address on GOV.UK, which tells you what insurers will see. Surface water and river risk are assessed separately.
What Flood Re does and does not do
Flood Re is a reinsurance scheme designed to keep home insurance affordable in high-risk areas. It is aimed at properties insured as homes, and buy-to-let property is generally outside the scheme, which is why landlords in flood areas need specialist cover.
Resilience work changes the terms
Flood doors, raised sockets, non-return valves and hard flooring all reduce what a flood costs to put right. Insurers will often reprice once the work is documented.
Expect a separate flood excess
The flood excess is commonly far higher than the standard excess. Compare that figure specifically, because it determines whether the cover is useful.
05
What if You Have Been Declined or Had a Claim?
A previous decline narrows your options but rarely closes them, provided you disclose it and can evidence what has changed.
Declines and cancellations
Insurers ask whether cover has been declined, cancelled or renewed on special terms. Answer accurately, because these questions are checked and a false answer voids the policy.
Subsidence history
Past movement is insurable where it has been investigated and resolved. Engineering reports, details of any underpinning and a certificate of structural adequacy all improve the terms.
A run of small claims
Three escape of water claims in five years affects appetite more than one large fire. Showing what has been done since, such as replaced pipework, changes the conversation.
Your own circumstances
Unspent convictions, previous insolvency or County Court judgments are standard questions. They affect which insurers will quote rather than whether cover is available at all.
06
How Do Insurers Assess an Unusual Risk?
They underwrite it individually rather than by computer, which is why evidence and a clear description matter more than they do on a standard property.
Referred rather than rated
Standard property is priced by a rating engine in seconds. A non-standard risk is usually referred to an underwriter who reads the detail and decides, so the quality of the information changes the answer.
What an underwriter looks for
Construction described precisely, the cause of any past damage, what was done about it, and who did the work. Vague answers get loaded or declined.
Surveys are common
On unusual or higher-value property, expect the insurer to want a survey or to send one. Treat it as an opportunity to evidence good condition rather than an obstacle.
Conditions may be attached
Cover is often offered subject to conditions, such as a minimum standard of locks, a chimney sweeping schedule or a maximum unoccupied period. Breaking a condition is different from breaking an exclusion, and it can invalidate the whole policy.
Terms improve with a track record
An insurer who loads a risk heavily in year one will often reduce it after two clean years. Staying with a specialist and building a record usually beats churning annually.
07
What Is Not Covered by Non-Standard Landlord Insurance?
Known defects, damage that has already happened, undeclared material facts and anything specifically excluded as a condition of the offer.
-
Existing damage and known defects
A crack you already know about, or a roof already failing, is not an insurable uncertainty. Insurers will exclude the known issue and cover the rest.
-
Specific exclusions applied to the offer
Cover on a non-standard risk is often offered with a peril excluded or a higher excess attached. Read those terms carefully before accepting.
-
Undeclared material facts
Anything you were asked about and did not disclose. On non-standard risks this is the leading cause of refused claims.
-
Long periods standing empty
Unoccupancy is rated separately, and a non-standard property left empty usually needs cover written for that.
08
How Much Does Non-Standard Landlord Insurance Cost?
More than standard cover, with the size of the difference depending on which factor pushed the property outside standard underwriting.
What moves the price
- 1 Timber or steel frame Modest loading, several insurers available
- 2 Concrete or prefabricated panel Larger loading, specialist market
- 3 Thatch Substantial loading, few insurers
- 4 Flood history Higher premium and a large flood excess
- 5 Subsidence history Higher subsidence excess, sometimes an exclusion
- 6 Previous decline Narrows the market rather than setting the price
- 7 Long void periods Raises it and narrows cover
Why evidence pays for itself
A structural engineer’s report or a flood resilience survey costs money once and can reduce the premium every year after. On non-standard risks the documentation is worth more than shopping around.
Comparing matters more here
Appetite varies enormously between insurers on these risks, far more than on standard property. Guidance from the Association of British Insurers is a useful reference on how unusual risks are underwritten.
09
How Can You Move a Property Back Toward Standard Terms?
Fix and document what can be fixed, keep a clean claims record, and re-present the risk with evidence at each renewal.
Deal with the underlying issue
Resolved subsidence, a replaced flat roof or completed flood resilience work all change the rating. The key is documentation, not just the work.
Keep a clean claims record
Small claims cost more in future premium than they return. On a non-standard risk, absorbing a minor loss is often the better decision.
Maintain and record
Regular inspections, servicing and prompt repairs, all logged. A well-documented maintenance record is the single most persuasive thing you can show an underwriter.
Re-present the risk annually
Do not simply renew. As evidence accumulates, insurers who declined before may quote, and the terms usually improve year on year.
Questions
Frequently asked questions
What makes a property non-standard?
Anything outside ordinary brick or stone walls with a tiled or slated roof. Timber frame, concrete panel, steel frame, thatch, flat roofs over a large area and listed status all count, as do flood history and previous subsidence.
Can I still get cover if I have been declined?
Usually yes. A decline by one insurer reflects that insurer’s appetite rather than the property being uninsurable, and specialist providers write these risks deliberately.
Do I have to declare a previous decline?
Yes. Insurers ask whether cover has ever been declined, cancelled or had special terms imposed, and failing to disclose it is the fastest way to have a later claim refused.
Does flood risk make a property uninsurable?
Rarely. It usually means a higher premium and a large flood excess. Flood Re exists to help with home insurance in high-risk areas, though it does not cover properties insured as buy-to-let.
What if the property has had subsidence?
Cover is available, normally with a higher subsidence excess and sometimes an exclusion for the affected part. Engineering reports and evidence that the movement was resolved make a real difference.
Is a flat roof a problem?
A small flat roof over an extension is usually fine. A property that is largely flat-roofed narrows the market, and insurers will ask about the covering, its age and its condition.
Does my own history affect it?
It can. Unspent criminal convictions, previous insolvency or a history of claims are all questions insurers ask, and honest answers get you to the right insurer faster.
Will it cost much more?
It usually costs more than standard cover, though how much depends on the reason. A timber-framed house is a modest loading, while a property with recent subsidence in a flood plain is a different conversation.
Can I get non-standard cover for an HMO or holiday let?
Yes. Non-standard refers to the risk rather than the letting type, so a thatched holiday cottage or a concrete-panel HMO both fall here.
What information should I have ready?
Construction details, any surveys or engineering reports, the claims history with dates and amounts, and details of any remedial work carried out. The more evidence you provide, the better the terms.
Does it cost anything to compare quotes here?
No. Comparing is free and there is no obligation to buy. We may be paid a fee when a policy is taken out, which does not change the price you are quoted.
Ready to compare quotes?
Cover for property that falls outside standard underwriting, whether because of its construction, its history, its location or yours.
Compare landlord insurance quotes from UK providers.