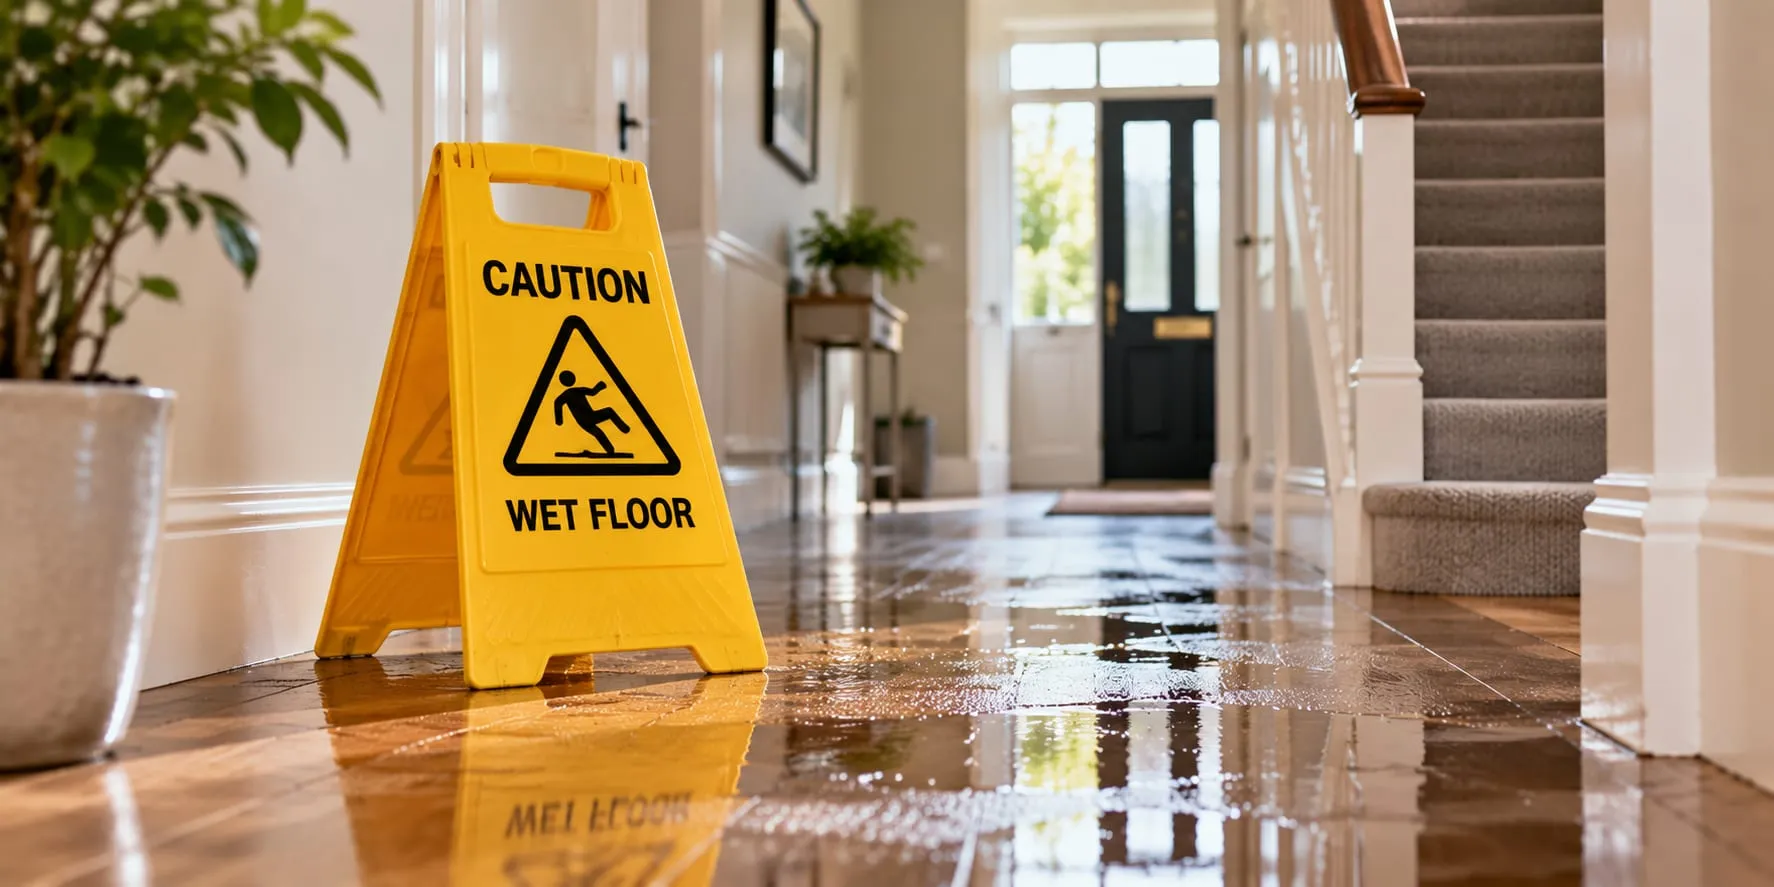
Cover for claims made against you
Landlord Liability Insurance
Property owners liability cover for claims brought by a tenant, visitor or neighbour who says your building caused injury or damage.
- Claims from tenants, visitors, contractors and neighbours
- Legal defence costs normally included
- Compare quotes from 40+ providers
Partnered with Quotezone
What being partnered with Quotezone means LandlordQuote is a trading style of Simply Quote Comparison Ltd. We are partnered with Quotezone, a trading style of Seopa Ltd (FCA FRN: 313860). As an Introducer Appointed Representative of Seopa Ltd, we may be paid a commission if you request a quote through this website. We do not provide advice or make recommendations. Your choice of provider is entirely your own.Compare landlord insurance and deals from industry leading providers, including













01
What Is Landlord Liability Insurance?
Landlord liability insurance, usually sold as property owners liability, pays compensation and legal costs when someone is injured or their property is damaged because of a building you let.
It is the part of a landlord policy that protects you personally rather than the bricks. A buildings claim repairs the property; a liability claim answers for the harm it caused.
It is included as standard on almost all landlord insurance cover in the UK, so the question at quote is the limit rather than whether you have it.
02
How Do You Compare Landlord Liability Insurance Quotes?
Choose a limit that reflects the worst realistic case, then check whether legal costs sit inside or on top of it.
- 1
Describe the property and who uses it
Insurers want the property type, how many households live there and whether there are shared areas. Footfall drives the rating.
- 2
Declare the features that raise the risk
Swimming pools, hot tubs, balconies, lifts, steep stairs and open fires all matter. So do trees near a boundary.
- 3
Pick your limit of indemnity
Limits come in set bands, and the step up usually costs far less than people expect. Check whether your lease, agent or licence sets a minimum.
- 4
Check how defence costs are treated
Find out whether legal costs come out of the limit or sit above it. This is the detail that separates two otherwise identical quotes.
03
What Does Landlord Liability Insurance Cover?
It covers compensation you are legally liable to pay for injury or property damage arising from the premises, together with the cost of defending the claim.
Injury to tenants and their visitors
The most common claim. A loose handrail, an unlit communal stairwell or a defective boiler that causes carbon monoxide exposure all fall here.
Damage to neighbouring property
A boundary wall that collapses, a tile that falls onto a parked car, or an escape of water that reaches the flat below. Liability follows fault rather than ownership of the damaged item.
Injury to contractors and visitors
Anyone lawfully on the premises is owed a duty of care. Where an injury arises from the state of the building rather than the way the work was done, your policy is the one that responds.
Legal defence costs
Defending a claim costs money even when you win. Most policies fund solicitors and experts, and the wording will say whether that spend reduces your limit.
Compare in one place
See what liability cover is available for your property.
One set of questions, quotes back from UK providers.
04
What Are Your Legal Duties as a Landlord?
Two pieces of legislation do most of the work: the Occupiers' Liability Act 1957 and the Defective Premises Act 1972, and neither can be signed away in a tenancy agreement.
The duty to visitors
Under the Occupiers' Liability Act 1957 an occupier owes a common duty of care to lawful visitors, meaning the premises should be reasonably safe for the purpose they are there for. Where you retain control of common parts, that duty sits with you.
The duty to repair
The Defective Premises Act 1972 imposes a duty on a landlord with repairing obligations to take reasonable care that people are safe from defects. It applies where you knew, or ought to have known, about the problem.
Why records matter so much
Liability turns on what you knew and what you did. A log of inspections, reported defects and completed repairs is usually the difference between a defended claim and a settled one.
Employing people brings another duty
If you employ a cleaner, gardener or caretaker, employers' liability insurance is normally compulsory. The HSE guide to employers' liability explains who counts as an employee, which is not always obvious with regular contractors.
05
What Limit of Indemnity Should You Choose?
Higher limits cost relatively little, so the sensible approach is to insure for the worst realistic outcome rather than the most likely one.
How limits are offered
Insurers offer liability in set bands rather than letting you pick any figure. The jump from one band to the next is usually a small proportion of the total premium.
| Consideration | Points to a lower limit | Points to a higher limit |
|---|---|---|
| Property type | Single let, low footfall | HMO, block, or commercial |
| Shared areas | None, tenant controls everything | Communal stairs, lifts, grounds |
| Features | No pool, no hot tub, level access | Pool, hot tub, balconies, steep stairs |
| Requirements | None imposed | Lease, agent or licence sets a minimum |
| Cost of stepping up | Material to you | Small relative to the policy |
Why serious injury claims run high
A claim involving long-term injury includes care costs and lost earnings over a lifetime, not just an immediate payment. That is why liability limits look large compared with the value of the property.
Check what others require of you
Freeholders, managing agents and licensing schemes frequently specify a minimum limit. Meeting it is usually a condition of the lease or the licence rather than a choice.
06
What Is Not Covered by Landlord Liability Insurance?
Deliberate acts, contractual liabilities you took on voluntarily, employee injuries and damage to the property itself all sit outside the cover.
-
Damage to your own building
Liability cover answers to other people. Repairing your own property is what the buildings section is for.
-
Injuries to your employees
Employees fall under employers' liability rather than property owners liability. Holding one without the other leaves a gap if you have staff.
-
Liabilities you accepted by contract
Agreeing in a contract to accept responsibility beyond your legal duty may not be covered. Read indemnity clauses in management or maintenance agreements before signing.
-
Deliberate or reckless acts
Ignoring a reported defect for months moves a claim from unfortunate to indefensible. Insurers can decline where the conduct goes beyond negligence.
07
How Does a Liability Claim Work?
You notify the insurer as soon as an incident happens, they investigate and take over the defence, and any settlement is paid within your chosen limit.
- Step 1 You notify the insurer
- Step 2 They investigate and take over the defence
- Step 3 Settlement is paid within your limit
A worked example
A tenant reports a loose banister in January.
It is not fixed, and in March a visitor falls and breaks a wrist, bringing a claim for £18,000 including care and lost earnings. The insurer investigates, finds the defect was reported and not repaired, and settles within your limit. Defence costs are added, and whether they erode the limit depends on the wording.
Never admit liability
Report the incident and let the insurer respond. An informal apology accepted as an admission can undermine the defence.
Act on reports immediately
The single most useful thing a landlord can do is fix reported defects quickly and record it. Most liability claims that succeed involve a defect somebody had already flagged.
08
How Much Does Landlord Liability Insurance Cost?
On a standard residential let it is usually a small part of the overall premium, rising with footfall, shared areas and higher-risk features.
What moves the price
- 1 Limit of indemnity Higher limits cost more, but not proportionally
- 2 Property type HMOs, blocks and commercial cost more
- 3 Shared or communal areas Raise it, because you retain control
- 4 High-risk features Pools, hot tubs and lifts raise it
- 5 Claims history Previous liability claims raise it
- 6 Number of properties A portfolio policy can reduce the per-property cost
Bundled or standalone
For most landlords, liability comes as part of a buildings policy rather than separately. Standalone cover is mainly relevant where you own land or a building insured elsewhere.
09
How Can You Reduce Liability Claims?
Inspect regularly, fix reported defects quickly, control the risks you can see and keep a written record of all three.
Inspect and document
A periodic inspection with photographs picks up loose handrails, worn stair nosings and failing lighting before anyone is hurt. Date every record.
Respond to reports in writing
Acknowledge a reported defect, say when it will be fixed, and confirm when it was. That paper trail is the strongest evidence you acted reasonably.
Manage the obvious hazards
Lighting in shared stairwells, secure handrails, safe boundary walls and well-maintained trees prevent most claims. Where there is a pool or hot tub, written safety rules matter.
Use properly insured contractors
Check that anyone working on the property holds their own liability cover. Where you employ someone directly, arrange employers' liability rather than assuming it is covered.
Questions
Frequently asked questions
What is landlord liability insurance?
It is property owners liability cover. It responds when someone claims they were injured, or their property was damaged, because of the building you let, and it pays compensation and legal costs up to your chosen limit.
Is it a legal requirement?
Not by statute for a standard residential let. It is effectively unavoidable in practice, and freeholders, managing agents and local authority licensing schemes often require a minimum limit.
What limit should I choose?
Limits are usually offered in set bands, with higher limits costing relatively little more. Pick a limit that reflects the worst realistic case rather than the likely one, because the limit is the ceiling on what the insurer pays.
Is it the same as public liability?
They work the same way. Public liability is the general business term, while property owners liability is the version written for landlords and tied to the building rather than a trade.
Do I need employers’ liability as well?
If you employ anyone, such as a cleaner, gardener or caretaker, employers’ liability is normally a legal requirement. Using a genuinely self-employed contractor is different, but the distinction is not always obvious.
Does it cover injuries to my tenant?
Yes, where you are legally liable. A tenant injured by a faulty stair rail or a defective boiler you failed to repair is the typical claim.
What if a contractor is injured at the property?
Property owners liability can respond where the injury arises from the condition of the premises. The contractor’s own insurance deals with the way they carry out their work.
Am I liable if my tenant injures someone?
Generally not. Liability follows control and fault, so a tenant’s own actions are usually their responsibility rather than yours.
Does it cover damage to a neighbour’s property?
Yes, where your building is at fault. A wall that collapses onto a neighbour’s car, or a leak from your property that damages the flat below, are common examples.
Are legal defence costs included?
Defence costs are normally covered, though whether they sit inside or on top of the limit varies. Check the wording, because a large defence bill can eat into the compensation available.
Does it cost anything to compare quotes here?
No. Comparing is free and there is no obligation to buy. We may be paid a fee when a policy is taken out, which does not change the price you are quoted.
Ready to compare quotes?
Property owners liability cover for claims brought by a tenant, visitor or neighbour who says your building caused injury or damage.
Compare landlord insurance quotes from UK providers.